Signals
Quantinuum and IonQ in Q3 2026: +233% and +336%, two numbers that do not tell the same story
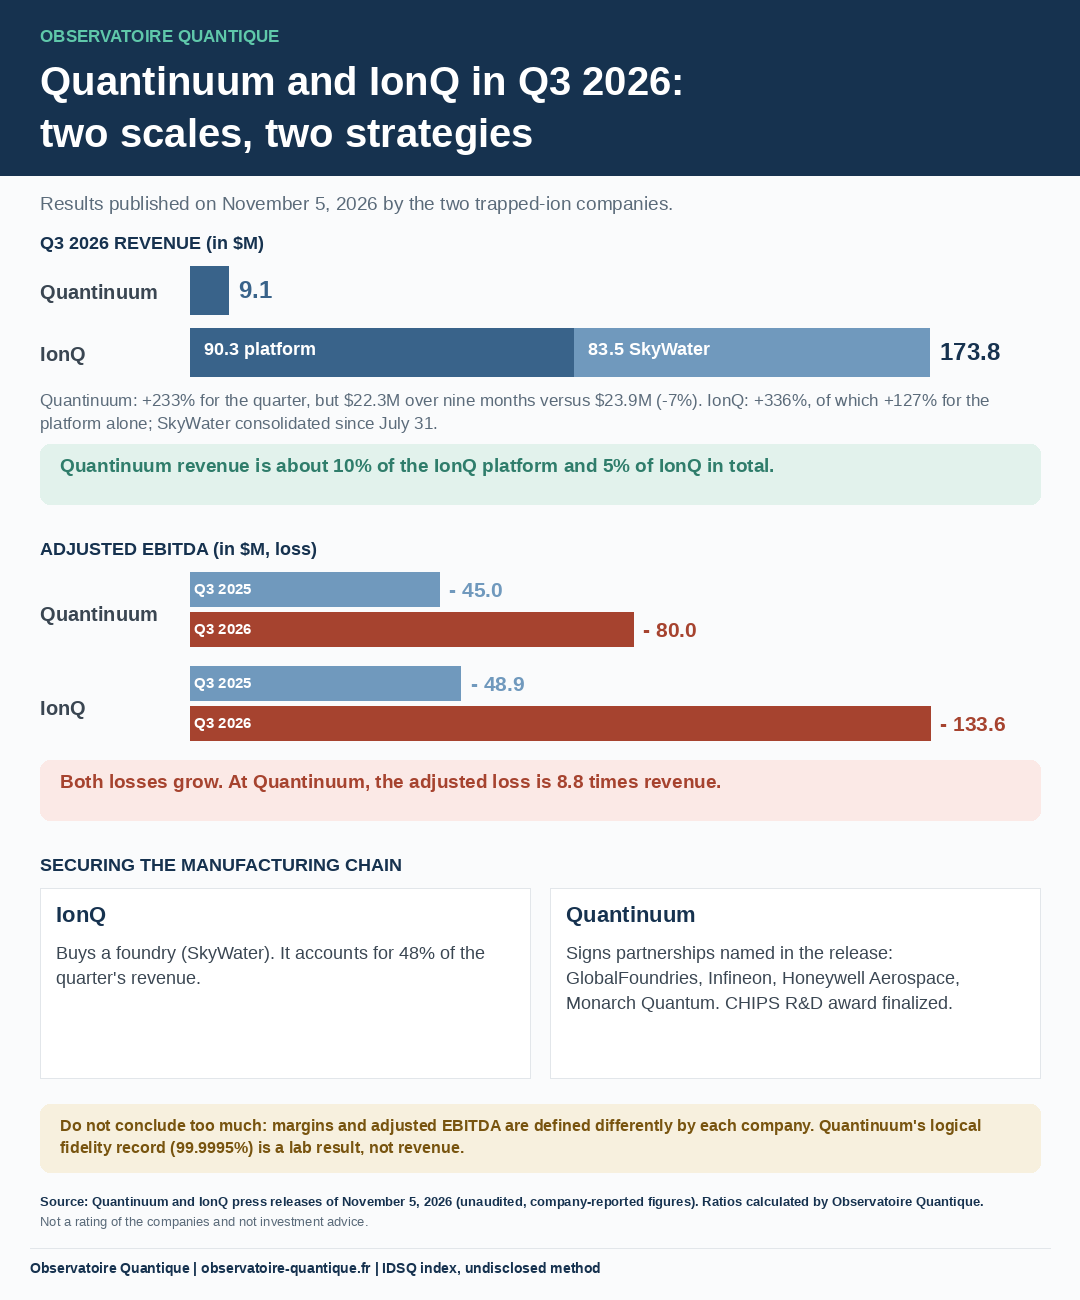
Quantinuum published on November 5, 2026 revenue of $9.1 million for the third quarter, versus $2.7 million a year earlier (+233%). Over nine months, revenue is $22.3 million versus $23.9 million a year earlier, about 7% lower: the cash flow statement shows $16.5 million of sales under a sales-type lease in the 2025 period. Full-year guidance is raised to $31 to $34 million (previously $28 to $32 million), which implies $8.7 to $11.7 million in the fourth quarter. The adjusted EBITDA loss is $80 million ($45 million a year earlier), the net loss is $118 million ($52 million) and cash is $1.94 billion at September 30. Operating cash flow is minus $229.9 million over nine months.
IonQ published the same day revenue of $173.8 million (+336% versus $39.9 million): $90.3 million from the IonQ platform (+127%) and $83.5 million from SkyWater, the acquired foundry, consolidated only since July 31. The +336% growth is therefore largely external. Adjusted EBITDA is minus $133.6 million (minus $48.9 million a year earlier). Cash and investments are $1.7 billion at September 30, or $3.7 billion after the $2.0 billion equity offering of October 16. On the same date, the comparison with Quantinuum is therefore $1.7 billion versus $1.94 billion, on slightly different scopes (cash and investments on one side, cash alone on the other).
Scales differ: Quantinuum's quarterly revenue is about 10% of the IonQ platform alone and 5% of IonQ in total.
Our angle is the manufacturing chain. IonQ buys a foundry. Quantinuum names in its release partnerships with GlobalFoundries, Infineon, Honeywell Aerospace and Monarch Quantum, and says it finalized the CHIPS R&D award as the only trapped-ion company selected. On materials, Quantinuum writes in its Helios blog that it switched its qubits from ytterbium to barium, to use visible rather than ultraviolet lasers. With the November 10, 2026 expiry of China's suspension of ytterbium controls, that is our reading, not a stated intention of the company.
On DARPA QBI, IonQ is in stage C (potential value up to $300 million, announced by DARPA on October 7), while Quantinuum continues its stage B contract and is discussing the scope of a stage C.
Sources: Quantinuum press release of November 5, 2026 (SEC) ; IonQ press release of November 5, 2026 (SEC) ; Quantinuum blog on Helios